Custom health plans with ICHRA

ICHRA (also known as CHOICE Arrangements) is a customizable, flexible, and personalized health benefit that allows employers to reimburse employees for their health insurance premiums and medical expenses.
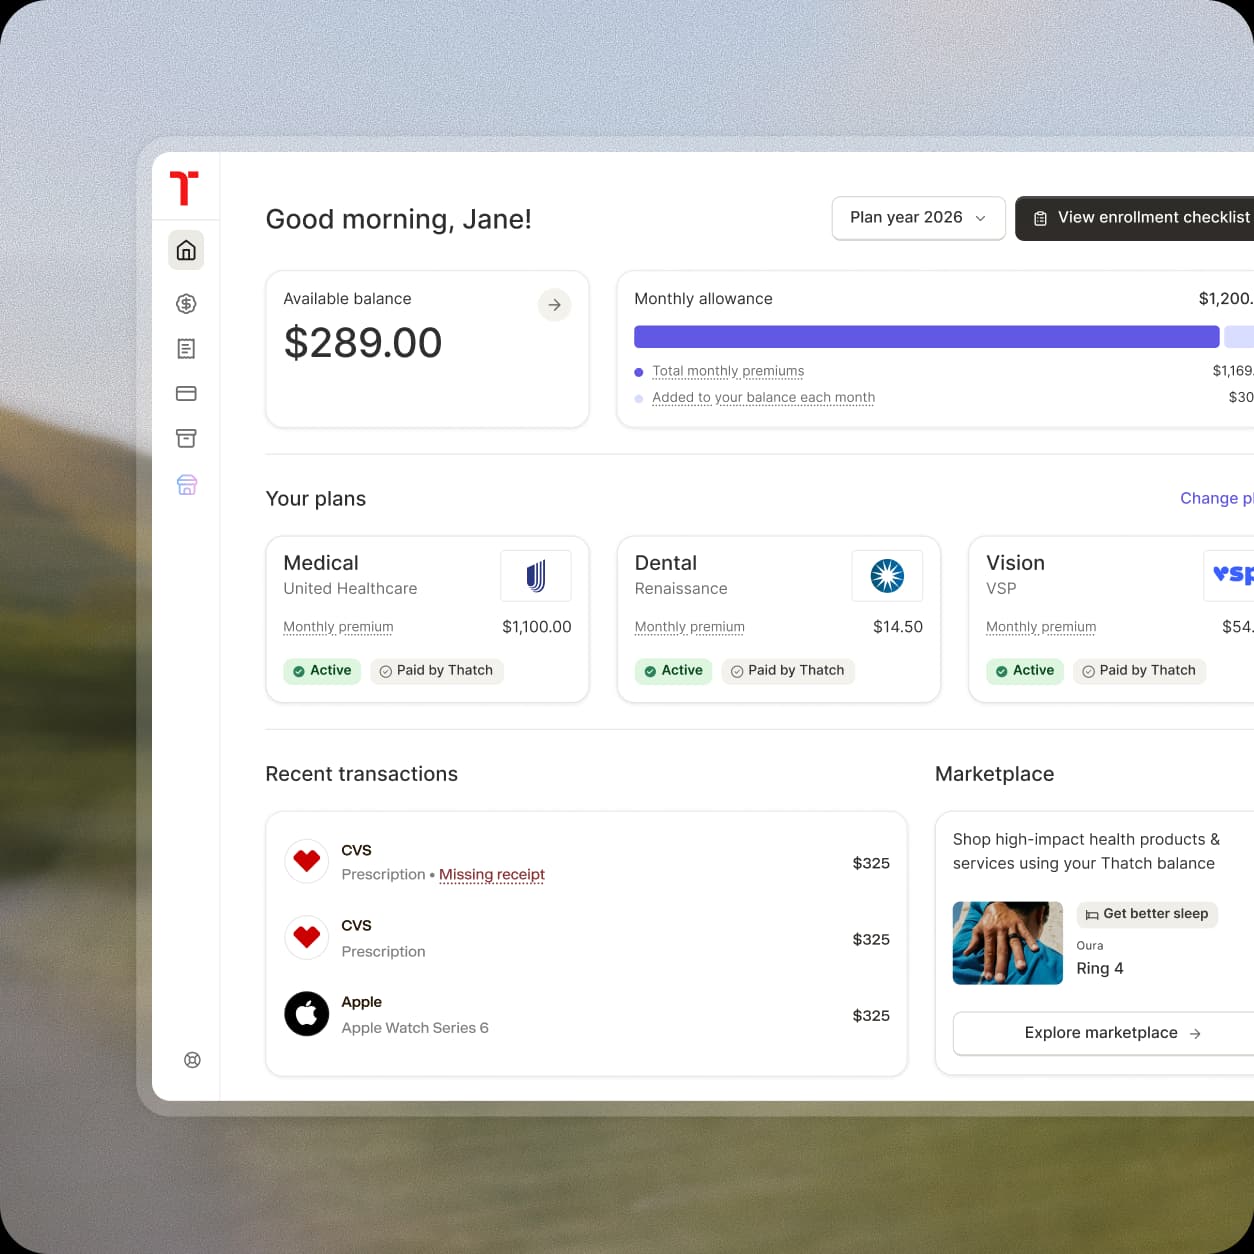
hero image

Why businesses are switching to ICHRA with Thatch

Say goodbye to rising premiums and inflexible coverage. ICHRA (also known as CHOICE Arrangements) gives your company a smarter way to offer healthcare — one that adjusts to your budget and your workforce. Thatch helps you launch fast, stay compliant, and deliver benefits that scale with your business.
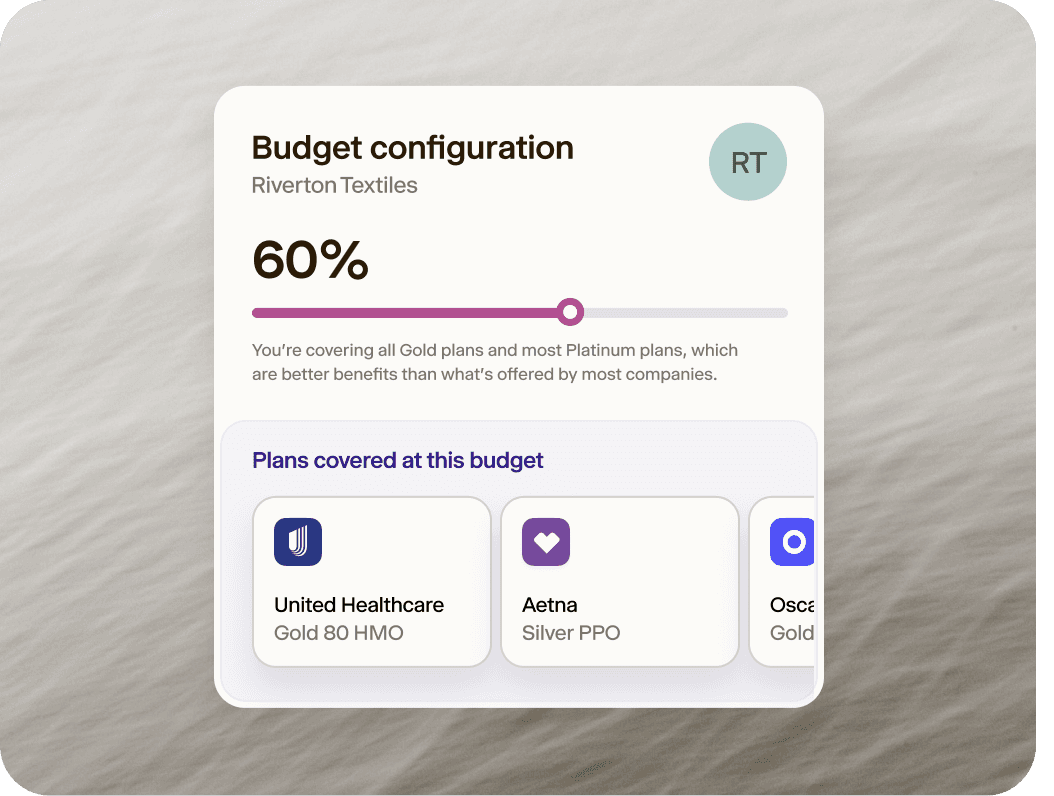
Why businesses are switching to ICHRA with Thatch

Tailored benefits for every team — From HQ to remote

Different roles need different benefits. With Thatch, you can segment employees by team, location, or status — and assign budgets that match their needs. Whether you’ve got remote workers, part-timers, or multiple offices, we make benefit customization simple and scalable
Tailored benefits for every team — From HQ to remote

ICHRA reporting guide

ICHRA (also known as CHOICE Arrangements) comes with compliance and reporting requirements that employers need to be aware of, including ACA, PCORI, ERISA, and Medicare Part D reporting. This ICHRA guide breaks down these obligations and shows how Thatch streamlines the process, making it easier for employers to stay compliant.
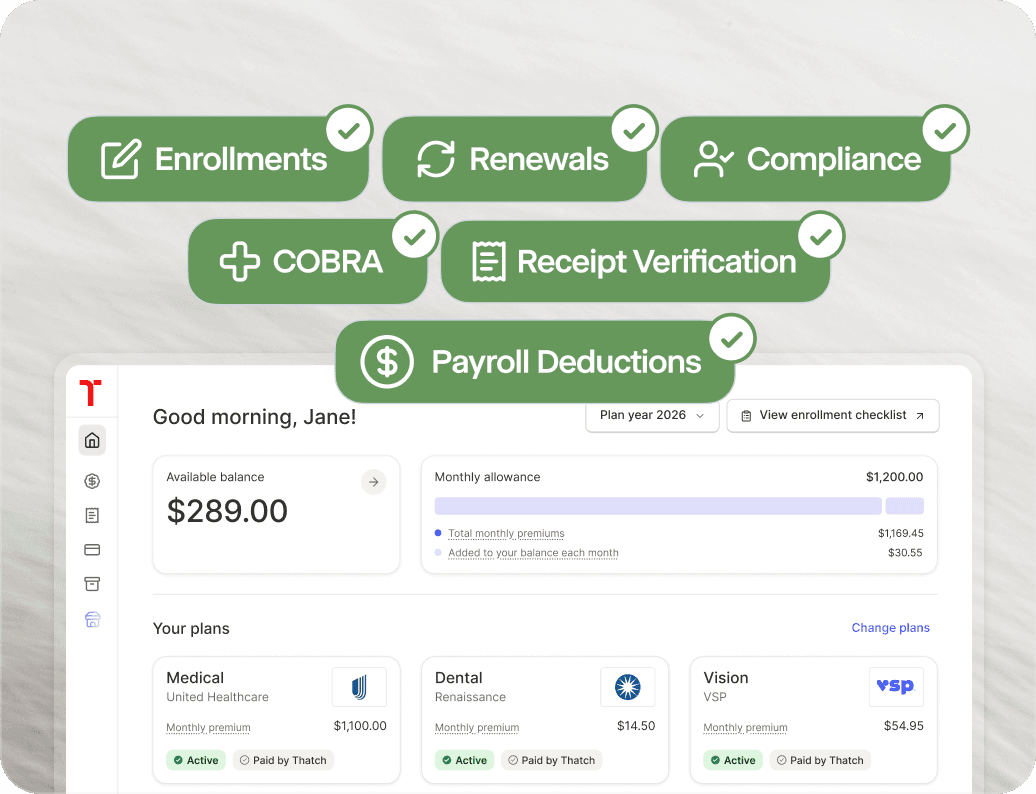
ICHRA reporting guide

ICHRA vs group plans

Traditional group plans are costly, rigid, and hard to manage. With ICHRA through Thatch, you set the budget, give employees choice, and eliminate the insurance admin from your to-do list. It’s health benefits — upgraded for today’s teams and budgets. Explore more here.

Cost Control

Set a defined budget for each employee to avoid annual rate hikes

ICHRA

Group Plans

Ease of Administration

Shift administrative burden to the individual insurance companies

ICHRA

Group Plans

Participation Flexibility

Avoid minimum participation requirements

ICHRA

Group Plans

Customization

Employees can select a plan that aligns with their specific healthcare needs

ICHRA

Group Plans

Employee Empowerment

Employees can use leftover funds for other healthcare expenses

ICHRA

Group Plans

We make ICHRA easy — you stay in control

ICHRA is a powerful tool — but only if managed well. That’s where Thatch comes in. We take care of setup, plan selection, reimbursements, compliance, and support. You stay focused on your team, while we deliver a seamless benefits experience in the background.
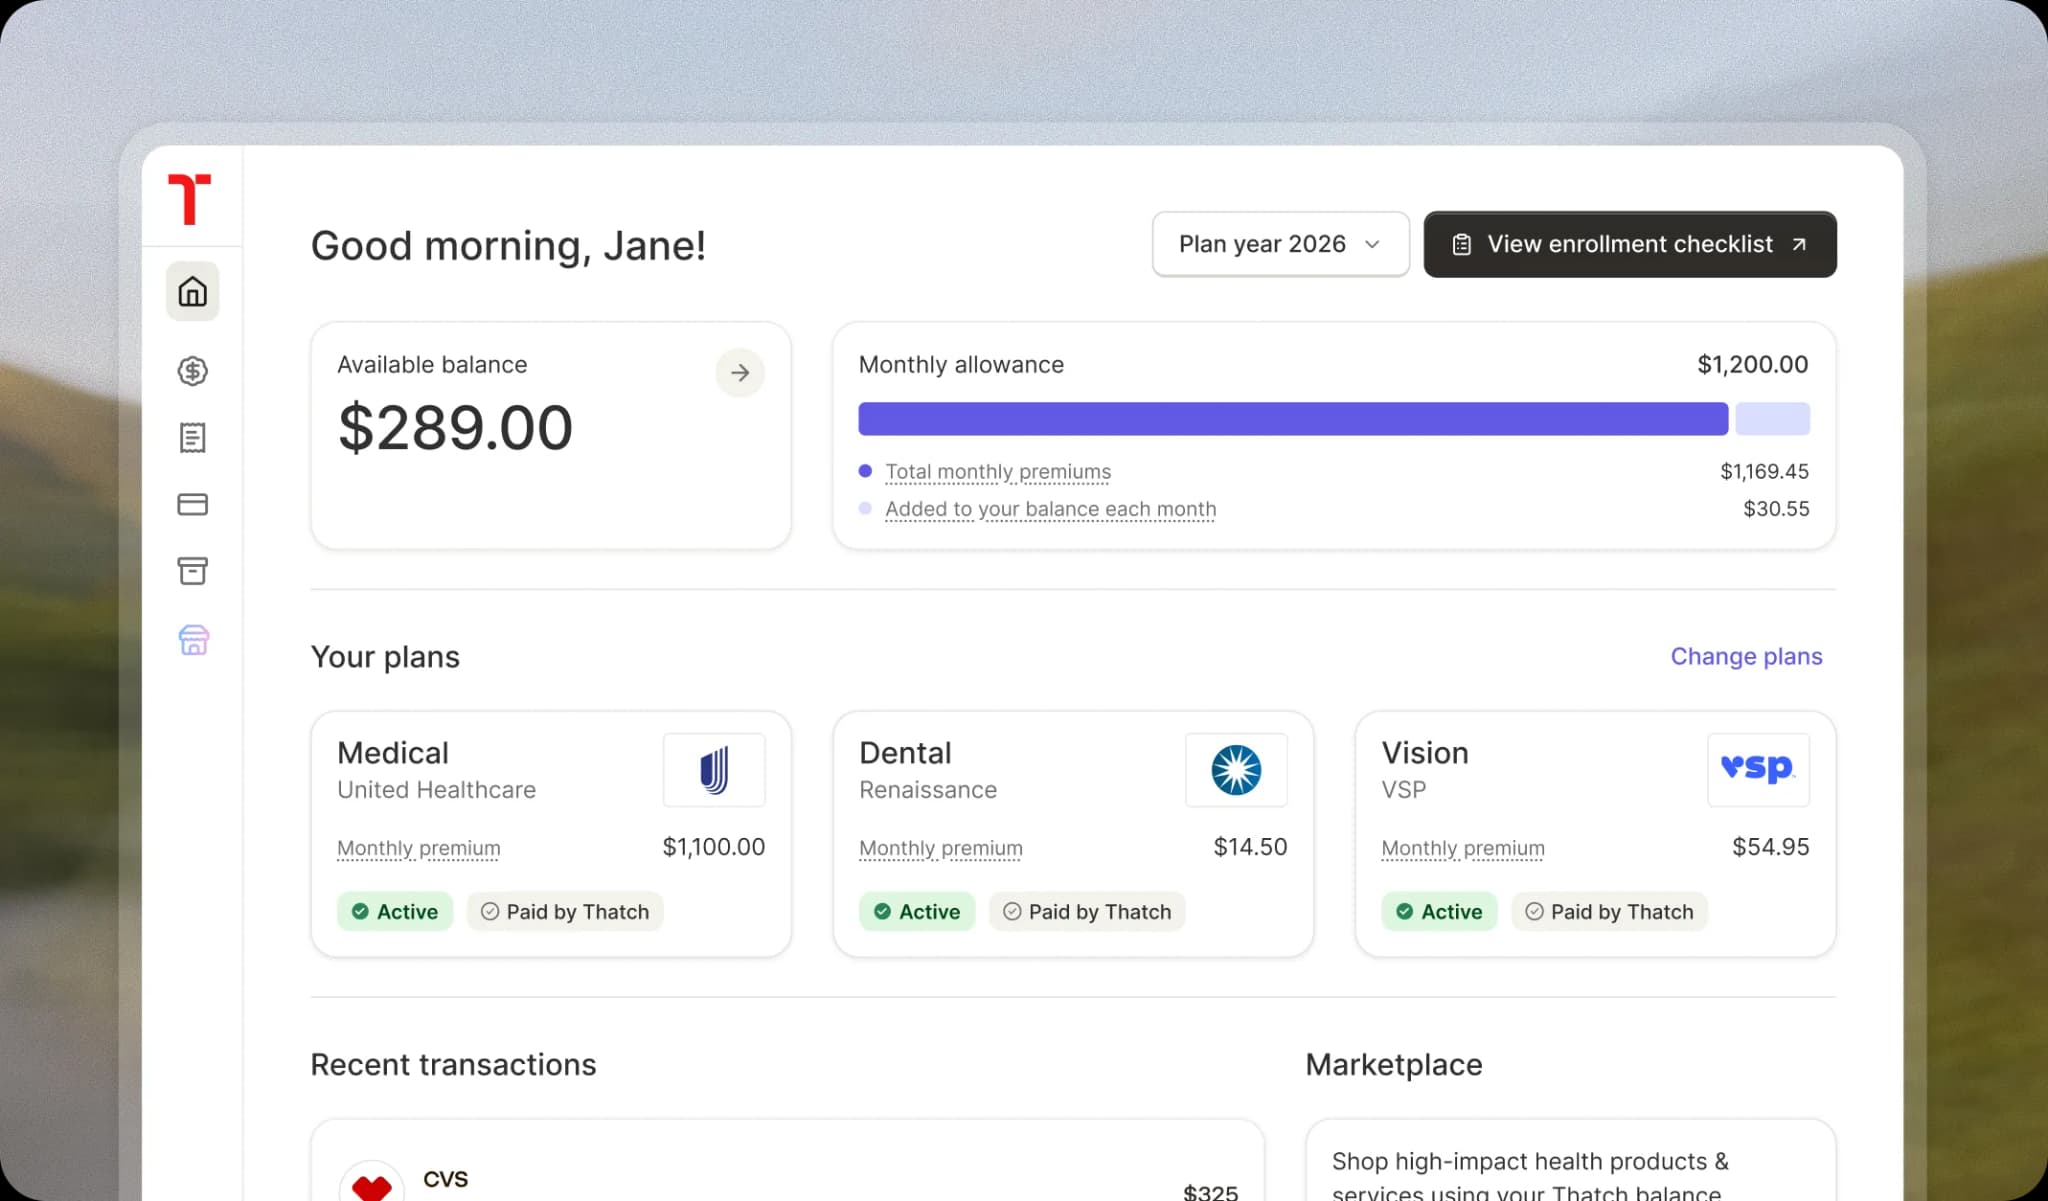
Thatch dashboard UI

Save money while providing better benefits

Most employers using Thatch save money with ICHRA compared to group health plans. ICHRA lets you set tailored allowances for each employee, preventing overspending in some markets and underspending in others.
Save money while providing better benefits

FAQ

Unlike group health plans, ICHRA can streamline administration and potentially increase employee satisfaction by providing more personalized health coverage options. See ICHRA vs Group Plans for a longer write-up on ICHRA vs group health plan.

Both are health reimbursement arrangements that allow employers to reimburse employees for their health insurance premiums and medical expenses on a tax-advantaged basis. ICHRA offers greater flexibility in terms of employer size, contribution limits, and employee eligibility criteria, making it a versatile option for a broader range of businesses. See ICHRA vs QSEHRA for more details on ICHRA vs QSEHRA plan.

Employers have the flexibility to set eligibility criteria for ICHRA. It can be offered to full-time, part-time, seasonal workers, and certain other classes of employees as defined by federal rules. Employers must offer ICHRA on the same terms to all employees within a class, with certain variations permitted for age and number of dependents.

Yes, and this is a big reason to use ICHRA. Reimbursements through HRAs are generally tax-free for both the employer and the employee, making it the only way to give your team pre-tax money for healthcare. If you instead just give your employees money to pay for their healthcare, that money is considered income and is taxable. Learn more about ICHRA vs healthcare stipends.

You can use ICHRA to reimburse employees for any qualified individual health plan. This includes plans purchased on Thatch, Healthcare.gov, or directly from an insurance carrier. View ICHRA plans available for your employees.

You have the ability to handle this however you like: you can permit unused allowances to roll over to the next period or expire.

Yes, you can. We generally recommend that employers allow employees to use their allowance for both premiums and medical expenses, both because this is a better experience for employees, but also because employees tend to max out the budget on the most expensive plan available to them otherwise.

No, employers can vary allowances based on different classes of employees, such as full-time, part-time, or by geographic location, among other criteria.

Yes, employers can offer both, but not to the same class of employees. For example, full-time employees could be offered a traditional health plan, while part-time employees could be offered ICHRA.

Employees submit proof of their medical expenses or insurance premiums to the employer or a third-party administrator like Thatch. Upon approval, they are reimbursed up to their allowance amount.

There are no maximum contribution limits for employers who offer ICHRA. However, federal rules require that large employers (those with more than fifty full-time employees) offer health coverage contributions that satisfy minimum standards, or face a penalty. We work with employers to facilitate a compliant and competitive ICHRA offer.

No, the ICHRA rules do not allow for this. You can only reimburse employees for their own premiums, but could provide a post-tax reimbursement separately.